A regulator's decision to cancel a Sydney auditor's New Zealand licence has put the old Greenfern Industries collapse back into public view, this time through the quieter but important machinery of financial-market oversight.
The Financial Markets Authority said it had cancelled Scott Bennison's licence to carry out financial markets conduct audits in New Zealand. The decision related mainly to his role as engagement quality reviewer for Greenfern Industries' group financial statements for the year ended 31 March 2024.
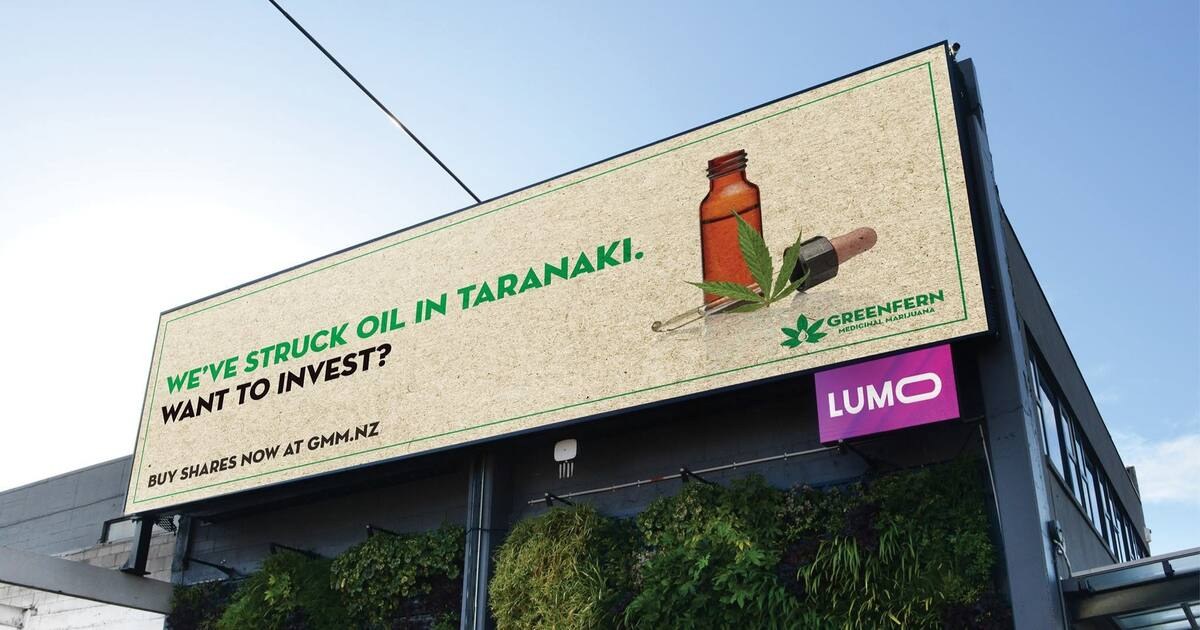
Greenfern was a Taranaki medicinal cannabis and biotechnology company that also operated in industrial hemp and hemp food. It was placed into receivership in February 2025 after failing to meet payment obligations. For investors, suppliers and former staff, the business story has already moved through the painful phases of collapse. The audit decision shows how the accountability questions can continue well afterwards.
Auditing often feels remote from the daily drama of a failed company. It should not. Public companies depend on outside audit work to give investors and the market confidence that financial statements have been properly tested. The engagement quality reviewer has a specific role in that system: checking that key judgements and audit work have been handled to the required standard before the audit opinion is issued.
FMA executive director of response and enforcement Louise Unger said the decision followed a statutory process and reflected the seriousness of the conduct identified. The regulator also noted that Bennison has a right to appeal to the District Court under the Auditor Regulation Act 2011.
That appeal right is important. A licence cancellation is a serious professional sanction, and the process should be tested if the affected auditor chooses to challenge it. But the existence of an appeal path does not lessen the public-interest point. The market needs to see that audit quality is policed, especially where a company later fails and questions about earlier financial statements become more sensitive.
The case also crosses the Tasman. Bennison was connected with Sydney-based accounting firm KS Black and Co, and the FMA thanked the Australian Securities and Investments Commission for cooperation. That is a practical signal for a small capital market. New Zealand companies, auditors and investors often operate across borders, and enforcement cannot stop at the water's edge.
For the medicinal cannabis sector, Greenfern's failure remains part of a broader warning about hype, capital pressure and execution risk in emerging industries. For listed-company governance, the lesson is more general. Growth stories need disciplined accounting, independent checking and boards that understand how much trust rests on the audit process.
The licence decision will not reopen Greenfern as a business. It does, however, underline that the clean-up after a collapse includes professional accountability. That is dull work until it is missing.