Lower-priced Chinese electric vehicles are pushing New Zealand's car market toward a new kind of competition: not only EV against EV, but new EV against older used petrol car.
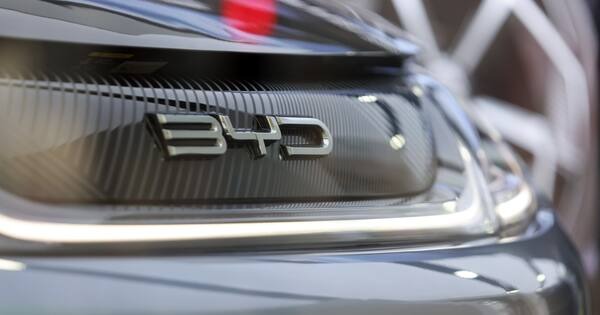
The latest 1News republication from The Conversation argues that vehicles such as BYD's electric Atto 1 are now close enough in price to disrupt the traditional logic of buying used. The point is not simply that EVs are becoming cheaper. It is that a credible new electric car can put pressure on the value of petrol cars below it in the price ladder.
That matters in New Zealand because the used import model has long shaped household car buying. The Conversation analysis notes that used imports made up 42 percent of the existing light-vehicle fleet in 2023, and almost 97 percent of used passenger-car imports came from Japan in 2025. For decades, New Zealand buyers have benefited from another country's early depreciation.
If China can produce new vehicles at prices that sit only modestly above older Japanese imports, the calculation changes. A household comparing an ageing petrol vehicle with a new electric model is no longer weighing only emissions or fuel savings. It is also weighing warranty, safety technology, battery confidence, servicing needs and the possibility that the old vehicle may lose value faster.
The effect would not be evenly felt. Consumers may gain cheaper entry into newer cars and lower running costs. Local automotive businesses may face a more difficult transition. The article cites MITO's 2025 automotive industry report, which put the wider sector at more than 68,000 workers across about 15,000 businesses, contributing roughly $8 billion to GDP. Repair and maintenance alone employed about 23,400 people.
EVs do not remove the need for automotive work. They still need tyres, suspension, crash repairs, electronics support and careful maintenance. But they do reduce demand for some familiar internal-combustion work: oil changes, exhaust systems, spark plugs and many engine and transmission repairs. That is a major skills question for workshops, training providers and parts suppliers.
The transition is also a local-economy question. New Zealand manufactures essentially no mass-market passenger cars, so much of the production value from the new technology sits offshore. The businesses most exposed to disruption, however, are local: mechanics, dealers, fuel retailers, parts distributors and wreckers.
China already supplied 73 percent of New Zealand's fully electric vehicle imports in the year to June 2026, according to the analysis. That figure suggests the shift is not a distant possibility. It is already visible in import patterns, even if the national fleet will take many years to turn over.
Policy discussion often focuses on chargers and emissions. Those are important, but they are not enough. Used-car values, scrappage rates, workshop revenue, technician training and regional access to EV servicing will show whether the transition is being absorbed smoothly or leaving local businesses to adjust alone.
The cheap-EV wave should not be treated as a crisis headline. Petrol cars will remain on New Zealand roads for decades. But it is a signal that affordability, technology and local employment are now tangled together. The car market is changing from the bottom up, and the businesses around it need time to change with it.